
Did you know that sending cash across borders now triggers a mandatory 1% federal excise tax in the U.S.? As of January 2026, the cost of staying traditional just went up. Meanwhile, the global average for remittances still sits at a staggering 6.36 percent. You're likely tired of watching your money vanish into hidden currency spreads while waiting five days for a bank to verify cross border p2p payments. It's frustrating when financial systems feel designed to keep your funds stuck behind legacy walls, especially when you need to reach family in restricted regions like Cuba.
We believe you deserve control, speed, and absolute transparency. This guide reveals how modern apps are dismantling these borders to provide a faster, cheaper, and more secure experience. You'll discover how to bypass the 3-5 day waiting periods and access instant fund availability through the latest digital infrastructure. We will compare the best tools for 2026, focusing on transparent fee structures and the ability to pay via Apple Pay, Google Pay, or crypto. It's time to move your money at the speed of your digital life.
Key Takeaways
- Say goodbye to the 3-5 day bank delay and start moving your money instantly across any border.
- Stop losing value to hidden exchange rate markups and switch to a transparent, flat-fee model.
- Use cross border p2p payments to send funds to Cuba and other restricted regions without the need for physical cash pickup.
- Protect your digital assets with high-tech security features like biometric authentication and integrated two-factor protocols.
- Empower your e-commerce business by connecting global payment APIs to your Odoo or WooCommerce storefront.
Beyond Banks: The Rise of Instant Cross-Border P2P
Imagine your money moving as fast as a text message. That is the reality of cross border p2p payments in 2026. We've finally moved past the era of intermediary banks holding your funds hostage for days. P2P transfers are direct. They connect your digital wallet to your recipient device instantly. The old 3-5 business day standard is officially dead. It was a relic of a paper-based era that simply doesn't fit our digital lifestyle. You aren't just a remittance sender anymore; you're a global digital citizen. You demand frictionless finance. This means value that flows at the speed of the internet, unburdened by legacy borders and bureaucratic delays.
The Death of the SWIFT Monopoly
The traditional SWIFT network is a maze of correspondent banks. Each stop adds a fee and a delay. Modern P2P apps solve this through local liquidity pools. Instead of sending money across an ocean, the app matches your request with existing funds already in the destination country. It's a clever bypass that keeps your capital moving. Instant settlement layers in 2026 fintech ensure the transaction is finalized in seconds. You avoid the toll booth fees of the old banking system. This decentralized approach means you don't pay for a bank's overhead. You only pay for the service you use. It's efficient, transparent, and liberating.
Value Beyond Cash: Top-ups and Gift Cards
In 2026, value isn't just a currency balance. In many emerging markets, mobile recharges have become a primary form of value transfer. They act as a stealth form of cross border p2p payments. Sending an international mobile top-up via DUC App provides immediate utility. It keeps families connected and provides a liquid asset that can be used for data or communication instantly. Digital gift cards follow a similar path. They enable borderless shopping without the need for a local bank account. You can send a gift card for a global retailer and your recipient can use it immediately. This ecosystem removes the obstacles of traditional physical cash pickup. It turns your smartphone into a global gateway for goods and services.
This shift represents a fundamental change in how we perceive international transfers. We are no longer limited by the physical location of a bank branch. We are limited only by our connection to the network. By embracing these digital-first tools, you regain control over your financial destiny. You choose the speed, you choose the method, and you see the fees upfront. That is the promise of the modern P2P revolution.
P2P vs. Traditional Remittance: A 2026 Performance Breakdown
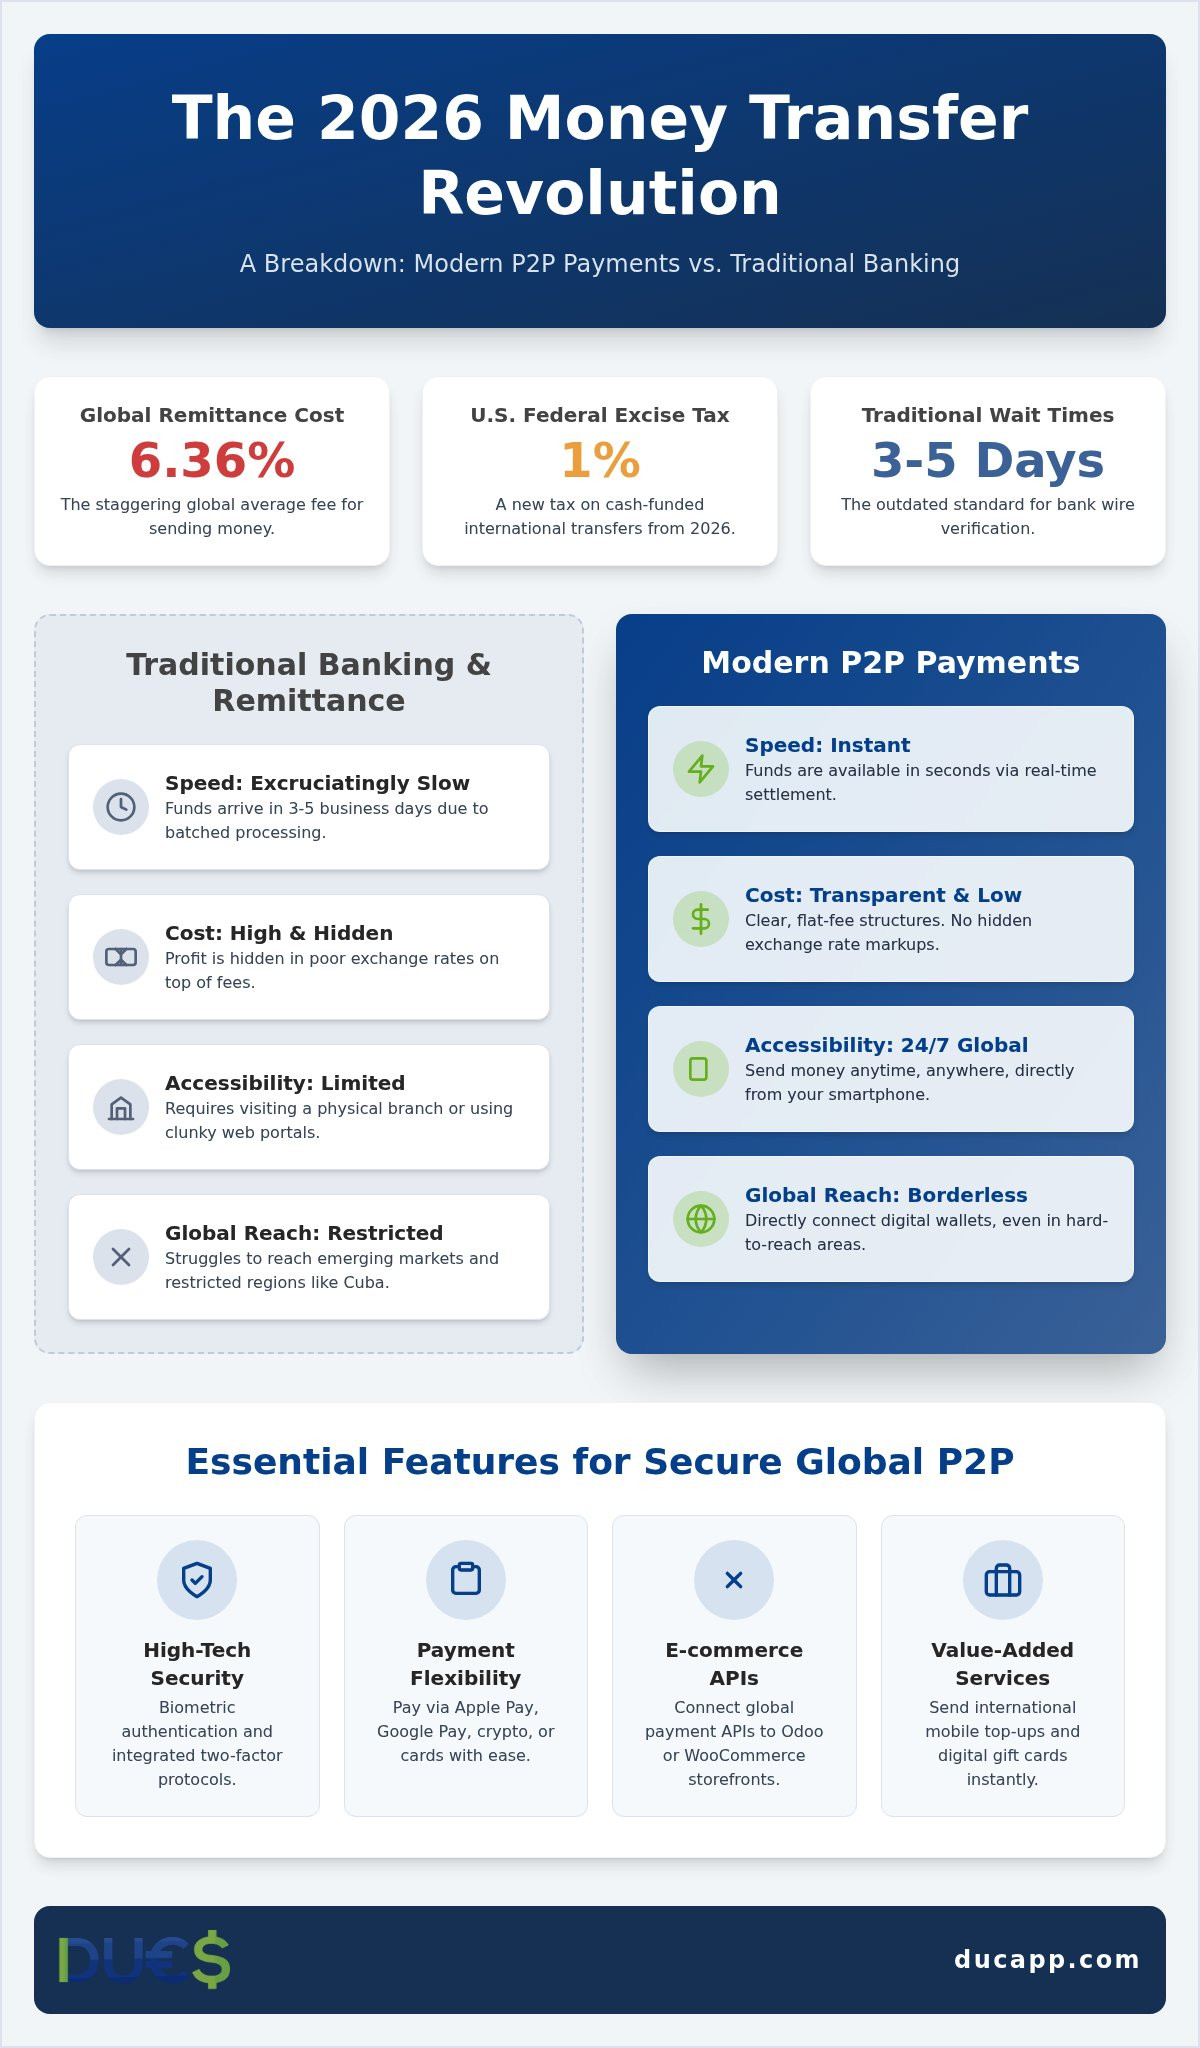
Choosing between a bank wire and a mobile app shouldn't feel like a gamble. In 2026, the gap between traditional banking and modern P2P has widened into a canyon. Bank wires rely on the aging SWIFT network; legacy remittance services often still require a physical trip to a storefront. Furthermore, as of January 2026, cash-funded international transfers from the U.S. now trigger a 1% federal excise tax. Modern cross border p2p payments, however, live entirely on your phone and avoid these extra costs by using digital funding sources like debit cards or crypto. You aren't just choosing a tool. You're choosing between staying tethered to a desk or moving your money with total autonomy.
The Speed Factor: Real-Time vs. Batched Processing
Banks love batching. They group transactions together to save on their own processing costs, which is why your transfer often takes days to clear. Modern apps settle in real-time. This isn't just about convenience; it's about business agility and family emergencies. The 2026 P2P revolution has turned "eventual" delivery into "instant" availability. If you need funds in a recipient's hands now, the legacy system is no longer a viable option. Digital-first platforms ensure your value moves at the speed of your internet connection.
Fee Transparency: Reading the Fine Print
Don't get fooled by "zero fee" marketing. Most legacy providers hide their profit in the conversion spread. They might charge a small flat fee but then offer an exchange rate that's significantly worse than the mid-market rate. With the global average remittance cost sitting at 6.36%, these hidden markups add up quickly. High-tech platforms prioritize transparency. You see the exact rate and the final amount before you hit send. This clarity is why many users now manage their global transfers through specialized digital hubs instead of traditional bank accounts. It's about keeping more of your money where it belongs.
How do you decide which method to use? Follow this simple framework for 2026:
- Use Bank Wires: Only for massive, non-urgent corporate transfers where legacy compliance is the only path.
- Use Legacy Remittance: If your recipient lacks a digital device and absolutely requires a physical cash pickup.
- Use Modern P2P: For everything else. It's the standard for speed, low fees, and 24/7 accessibility.
By shifting to cross border p2p payments, you bypass the bureaucratic hurdles that have slowed down global commerce for decades. It's a more efficient way to live and work in a borderless world.
Essential Features for Secure Global P2P Transfers
Security in 2026 isn't just about a strong password. It's about a multi-layered defense that feels invisible to you but impossible for bad actors. When you engage in cross border p2p payments, you need to know your assets are shielded by the latest tech. Non-negotiable protocols now include biometric authentication like FaceID and hardware-based two-factor security. These features ensure that only you can authorize a transfer. A modern digital wallet must also support multiple currencies simultaneously. This allows you to hold USD, EUR, or even crypto in one place. Holding crypto-to-fiat options acts as a vital hedge against local inflation in volatile markets. It gives you the power to choose the most stable value for your savings. You shouldn't be forced to convert money until the moment you actually need to spend it.
Encryption and Fraud Prevention
Data privacy is a human right. Every transaction must use end-to-end encryption to keep your financial details private. This means your sensitive data is scrambled from the moment it leaves your device until it reaches the recipient. AI-driven fraud detection now works in the background. It analyzes millions of data points to stop suspicious activity instantly. It does this without blocking your legitimate transfers. A secure digital wallet app in 2026 must provide real-time threat monitoring and instant user alerts for every account change. This proactive approach builds the high-tech confidence you need to manage your money globally. You get peace of mind without the bureaucratic lag of old-school banks.
Payment Method Versatility
Your app shouldn't dictate how you pay. It should adapt to your preferences. A modern platform must integrate with Apple Pay and Google Pay for one-tap convenience. This allows for a seamless part of your digital lifestyle. Sometimes you need immediate liquidity to cover an unexpected cost. In those cases, sending money with a credit card is a powerful tool for instant funding. DUC App understands this need for flexibility. It supports diverse regional systems like SEPA for Europe and Interac for North America. This ensures that no matter where you are, your cross border p2p payments are supported by the payment methods you already trust. It's about removing friction and providing a guided, helpful experience for every user. You deserve a financial tool that works as hard as you do.
Solving the "Hard-to-Reach" Problem: Cuba and Emerging Markets
Sending value to restricted economies like Cuba has historically been a logistical nightmare. Traditional banks often refuse these transactions entirely. If they do accept them, they bury you in paperwork and delays. Cross border p2p payments have emerged as a vital lifeline for families in these regions. They offer a way to bypass the slow, expensive systems of the past. Instead of relying on physical cash pickup, which can be difficult or unreliable, these digital tools allow for direct value transfer. For Cuban families, MLC (Moneda Libremente Convertible) transfers are essential for purchasing basic goods. P2P technology isn't just about convenience here. It's a tool for financial empowerment in economies that are often cut off from the global stage. You regain the ability to support your loved ones without the typical bureaucratic interference.
The DUC App Advantage for Cuba
Staying connected shouldn't be a struggle. You can recharge Cubacel from the USA instantly to ensure your family never loses access to communication. DUC App stands as the reliable successor to legacy systems like Duales. It provides a familiar yet upgraded experience for long-time users. One of the most innovative features is email-based payments. This is a game-changer for recipients who might not have a traditional bank account but have access to a smartphone. It simplifies the process of receiving value and makes the entire ecosystem more inclusive. Ready to send support? You can start your first transfer today and see how easy it is to bridge the gap.
Navigating Regulations and Compliance
Moving money to restricted regions requires more than just good tech. It requires a deep understanding of international remittance laws. DUC App ensures every transfer is fully compliant with current regulations, including OFAC requirements as of August 2026. This balance between borderless technology and local legal requirements is what builds long-term trust. You don't have to worry about your funds being frozen or flagged. The platform handles the complex backend compliance so you can focus on your family. Transparency in regulatory adherence is a core value. It ensures that cross border p2p payments remain a sustainable solution for everyone involved. We believe in providing a secure, guided experience that respects both global laws and individual needs.
By focusing on these high-friction corridors, P2P apps are doing more than just moving money. They are creating a more equitable financial world. You are no longer limited by where your family lives. You are only limited by the tools you choose to use. Choose a partner that understands the specific challenges of your destination.
Transitioning to DUC App: Your Borderless Financial Hub
The era of waiting for your own money is finally over. Moving to the DUC App ecosystem means choosing movement over stagnation. It is the final step in your journey toward total financial liberation. You have seen the data. You have compared the fees. Now it is time to act. Transitioning your cross border p2p payments to a dedicated digital hub isn't just a tech upgrade. It's a lifestyle change. You are opting for a system that respects your time and your global connections. Leave the cold, bureaucratic formality of traditional banking behind. Embrace a tool that feels like a seamless part of your digital life. You deserve a partner that moves as fast as you do. To further simplify your financial life, you can explore Ratenkredit-Vermittlung for modern credit options that align with your digital lifestyle.
For the Individual: Instant P2P and Top-Ups
For the individual user, the experience is pure simplicity. Forget long account numbers, IBANs, or visiting physical storefronts for cash pickups. Send value using just an email address or a P2P username. It's fast. It's direct. It's liberating. You can also access a wide variety of digital gift cards 24/7 for instant global shopping or support. This versatility ensures you're never stuck without a payment option, regardless of where your recipient lives. Using a secure international money transfer app gives you the confidence to manage your wealth from anywhere. You get real-time updates and total control over every cent. It's a smart companion for a smart user.
For the Merchant: API and E-commerce Integration
Merchants and developers find a different kind of freedom within our ecosystem. Our global payment processing API is built specifically for the 2026 digital economy. It is scalable, well-documented, and ready for immediate deployment. If you run a store on WooCommerce or Odoo, our specialized plugins remove the friction of international sales. You can accept cross border p2p payments and settle them instantly. This improves your cash flow and opens your business to a global audience without the usual border friction. We invite developers to explore our sandbox environment. Test your checkout flows. Build your custom integrations. See how easy it is to integrate a borderless payment solution into your existing tech stack. Growth should not be limited by geography.
Stop settling for the limitations of the past. Download the DUC App today. Experience your first instant transfer and feel the difference of a financial tool designed for the modern world. Take control of your value. Live without the constraints of traditional systems. Your borderless future starts now.
Embrace the Future of Global Value
The financial landscape of 2026 demands more than just "sending money." It requires the fluid movement of digital value across legacy borders. You've seen how modern apps dismantle the 3-5 day waiting periods. They replace hidden costs with transparent, real-time settlement. By choosing cross border p2p payments, you regain absolute control over your global reach. Whether you're supporting family in Cuba or scaling an e-commerce brand, the tools for financial liberation are already in your hand.
DUC App reduces transfer times from days to seconds. It supports the payment methods you trust, including Apple Pay, Google Pay, and crypto. It's a platform trusted by thousands of families to bridge the gap to high-friction corridors with ease. This isn't just about efficiency. It's about living without the constraints of a bureaucratic past. You deserve a smart companion that understands the modern world. Move your money. Own your time.
Start your first borderless transfer with DUC App today. Join a community that values speed and total transparency. Your money should move as fast as your digital life. Take the first step toward a truly borderless future.
Frequently Asked Questions
What are cross border P2P payments and how do they differ from bank wires?
cross border p2p payments differ from bank wires by removing the intermediary toll booths of the SWIFT network. While banks take days to process, P2P transfers settle in seconds. You avoid the high fees associated with correspondent banking. It is a direct, user-to-user exchange that happens entirely within a digital ecosystem. This makes global transfers as simple as sending a text message.
Are cross border P2P payments safe to use for large amounts?
Modern P2P platforms are built with institutional-grade security protocols. They use end-to-end encryption to scramble your data and biometric authentication to ensure only you authorize transfers. AI-driven fraud detection monitors every transaction in real-time. This provides a secure environment that often surpasses the safety of traditional banking for large amounts. You get peace of mind without the bureaucratic lag of old-school systems.
How much are the typical fees for an international P2P transfer in 2026?
In 2026, the global average cost for remittances is 6.36 percent. P2P apps lower this by avoiding the 1% U.S. tax on cash-funded transfers and using local liquidity pools. You usually pay a transparent flat fee and a small conversion spread. High-tech platforms show you the exact total before you hit send. This eliminates the surprise charges often found in legacy wire transfers and intermediary bank fees.
Can I send money to Cuba using DUC App from the USA or Canada?
Absolutely. DUC App is a primary tool for sending funds to Cuba from the USA and Canada. It supports MLC account transfers and mobile recharges. The platform strictly follows international laws, including the latest OFAC regulations as of August 2026. It acts as a reliable successor to legacy systems like Duales. You can support your loved ones with total confidence in the legal compliance of your transfer.
What is the fastest way to send MLC to family in Cuba?
The fastest method is a direct P2P transfer to an MLC account. This bypasses the slow process of physical cash pickup and traditional bank clearing. DUC App processes these in seconds, giving your family instant access to funds. You can also use email-based payments for those without bank accounts. It is the most efficient way to navigate the hard-to-reach challenges of the Cuban economy while ensuring instant fund availability.
Do I need a bank account to receive money through a P2P app?
No, you don't need a traditional bank account to use a modern P2P app. Recipients can hold funds in a secure digital wallet or receive them via email payments. These funds can then be used for mobile top-ups, global gift cards, or even peer-to-peer exchanges. This digital inclusivity is a game-changer for unbanked individuals. It brings everyone into the global financial network through their smartphone without the need for bureaucratic paperwork.
How does crypto-to-fiat exchange work within a P2P payment system?
The app acts as a bridge between decentralized technology and local currencies. You can hold crypto in your wallet to hedge against inflation and convert it to fiat only when needed. When you initiate cross border p2p payments, the conversion happens instantly in the background. This ensures you get the best possible rate without manual trading. It is a smart, automated way to manage global value while avoiding traditional constraints.
What payment methods does DUC App support for international transfers?
DUC App supports a wide variety of modern payment methods for your convenience. This includes one-tap options like Apple Pay and Google Pay. You can also use Visa, Mastercard, or regional systems like SEPA and Interac. Crypto funding is also available for those seeking maximum flexibility. This diverse support makes the app a seamless part of your digital lifestyle, no matter where you are located or how you choose to fund your transfers.


